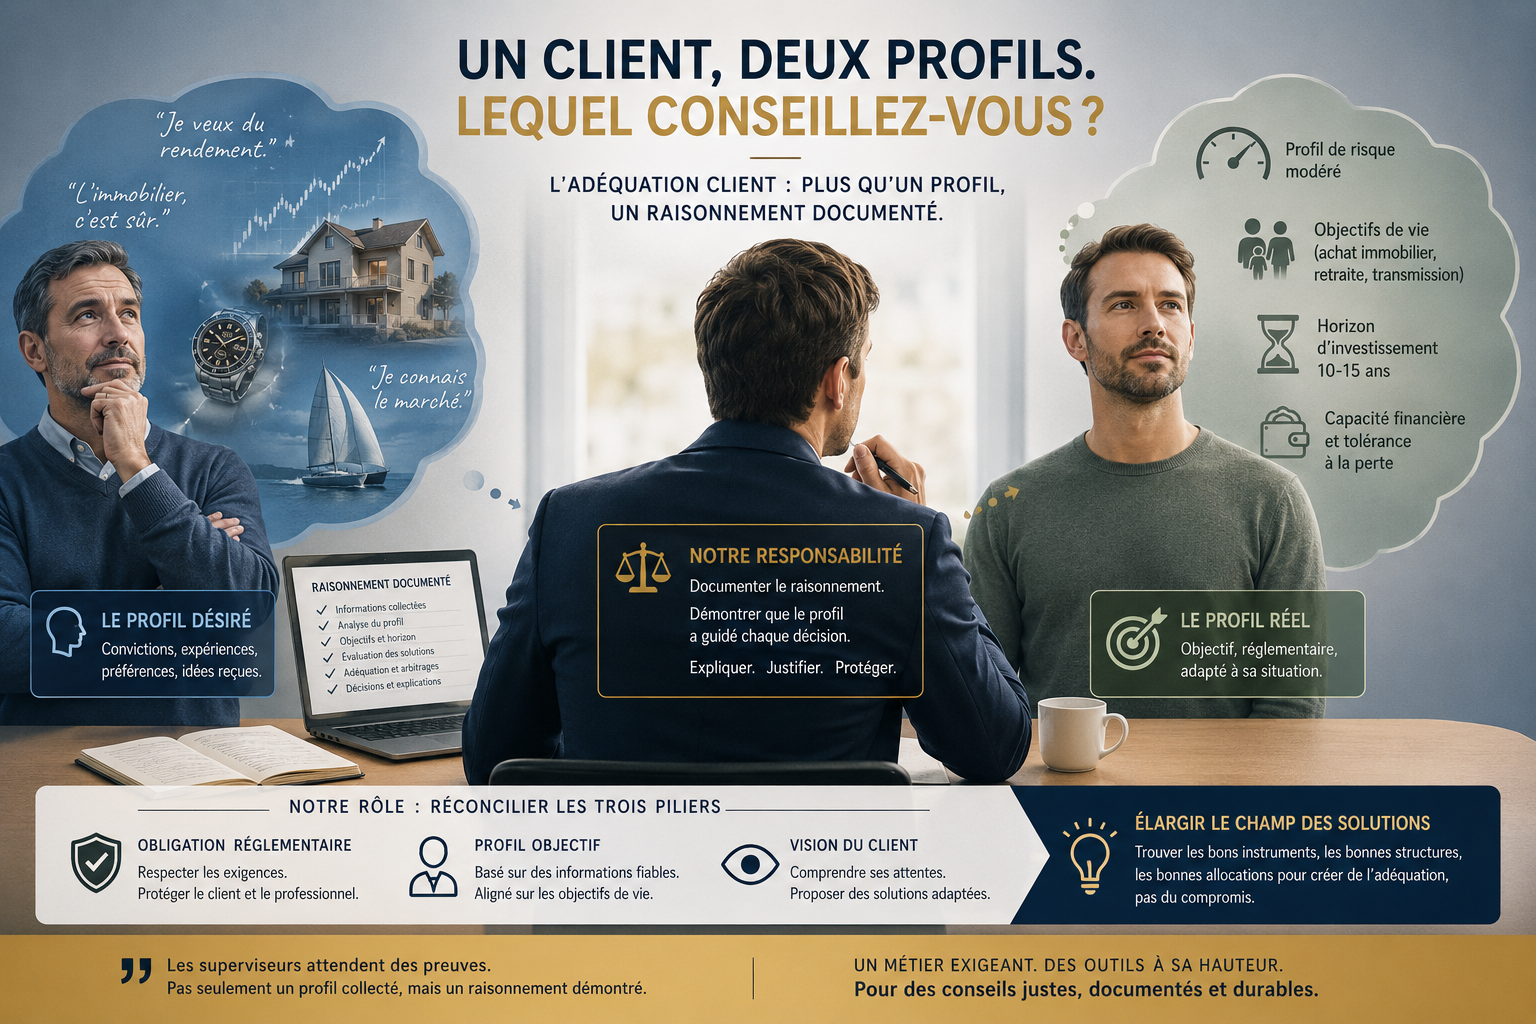
On May 6, 2026, ESMA published the conclusions of its Common Supervisory Action conducted in 2024 and 2025 on the integration of sustainability preferences into MiFID II suitability assessments. The finding is structural: while data collection frameworks are broadly in place, the documentation of decision-making rationale and the neutrality of advice remain insufficient across a majority of supervised firms.
This outcome points to a deeper limitation in how the framework is applied in practice. Suitability assessments are too often treated as isolated events, conducted at onboarding and periodically updated, whereas Article 25 of MiFID II and the ESMA suitability guidelines require continuous coherence between each investment decision and the client’s actual situation.
This requirement is particularly difficult to meet when the preferences expressed by the client diverge from their objective profile. The regulation does not explicitly resolve this tension between what the client wants and what their risk profile permits. It does, however, require the professional to document their reasoning, justify their choices, and demonstrate that they acted in the client’s best interest, including when that means departing from what the client originally requested.
For investment firms, tied agents, and discretionary portfolio managers, the obligation to trace and justify the decision-making process is now at the core of AMF and CSSF supervisory reviews. This week’s ESMA report is the clearest signal yet: the implementation phase is over. The evidentiary phase has begun.